Roof Insurance Claim Help From a Florida Roofing Contractor
When storm damage leads to an insurance claim, we inspect, document and estimate the roofing work for homes and properties across Southwest Florida, and we stay out of policy advice so you remain in charge of your claim with your insurer.
Or call us any time at (239) 449-3387.
License No.
Florida Roofing License #[License Number]
9 years
of Florida roofing experience
estimates
Itemized written estimates
24/7
24/7 emergency roofing
What Preventive Roof Maintenance Involves
Roof Insurance Claim Help That Keeps You in Control
After a hurricane or a hard summer storm, the roof is only half the problem. The other half is figuring out what's damaged and how to talk about it with your insurance company. Our roof insurance claim help in Florida focuses on the part we know best: the roof.
We inspect the damage, document what we find, and prepare an itemized estimate for the repair. Decisions about your policy and your claim stay between you, your insurer and any licensed professionals you choose to work with.
What Does a Roofer Do During an Insurance Claim?
A roofing contractor's job during an insurance claim is to show the roof's condition clearly and to complete the approved repair correctly. Here's how that works with us.
Step 1
Roof Inspection and Documentation
We inspect your roof after the storm and document visible damage, such as lifted or missing shingles, cracked tiles, loose metal and damaged flashing.
Step 2
Itemized Written Estimate
We provide a good-faith, itemized estimate of the materials and labor needed for the repair, as Florida law requires before any agreement for insurance-related roof work.
Step 3
On Site When the Adjuster Visits
If you'd like, we can be at your property when your insurance adjuster inspects the roof to point out the damage we documented.
Step 4
Repair Completed to Code
Once you're ready to move forward, we complete the roofing work to the Florida Building Code, with an owner involved throughout.

Where Our Role Starts and Where It Stops
Florida law draws a clear line around what roofing contractors can do in an insurance claim, and we follow it.
How We Help
- We inspect your roof and document visible storm damage.
- We provide an itemized written estimate for the roofing work.
- We explain the condition of your roof in plain language.
- We complete approved repairs or replacements to the Florida Building Code.
What Stays With You and Your Insurer
- We don't interpret your policy or advise you on what it covers.
- We don't adjust or negotiate your claim; that's the role of a licensed public adjuster.
- We never pay, waive or rebate any part of your deductible, or offer gifts or incentives tied to an inspection or a claim.
- We aren't an insurance company, a public adjuster or an attorney.
These limits come from Florida Statute (239) 449-3387, which governs how contractors can work with property insurance claims.
How to Document Roof Damage After a Storm
A few simple steps right after a storm make everything that follows easier.
- Stay off the roof and check for damage from the ground, where it's safe.
- Photograph damaged areas, debris and any interior water stains, and note the date.
- Take reasonable steps to prevent more water damage, such as placing buckets or covering belongings, and keep your receipts.
- Report the damage to your insurance company or agent promptly, and ask about reporting deadlines, which Florida law sets.
- Schedule a roof inspection so the damage is documented by a licensed roofer.
If water is coming in right now, call our 24/7 emergency roof repair line. For more on what storms do to roofs, see our storm damage repair page.
Why Homeowners Call Black Flag When Insurance Is Involved
Insurance-related roof work goes smoother with a contractor you can verify and reach.
We hold Florida Roofing License #[License Number], and we'll still be here long after the storm-chasing trucks leave town. You can verify our license with the Florida Department of Business and Professional Regulation.
Every estimate is itemized, so you and your insurer can see exactly what the repair includes.
Chris or Spenser stays involved from the first inspection through the finished roof, so you're never passed around.
Our 24/7 emergency roofing line helps stop further damage while the rest of the process gets underway.
What Our Neighbors Say After the Work Is Done
We'd rather you hear it from the homeowners we've worked with. These reviews come straight from Google, so you're reading them exactly as they were written.
Storm Season Neighbors, Not Storm Chasers
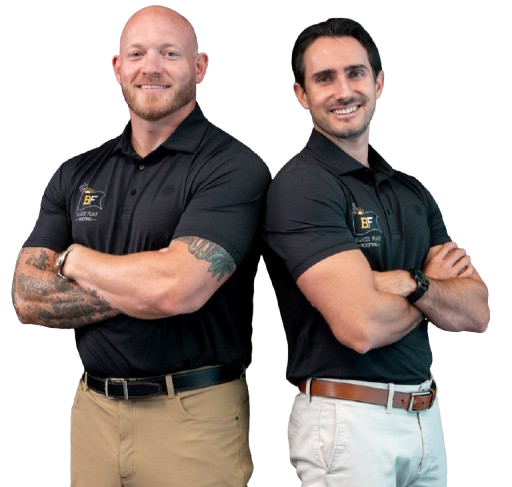
Black Flag Roofing is owned and run by co-founders Chris Little and Spenser Pollard, who live and volunteer in the Southwest Florida communities we serve. After a storm, you'll be working with people who were here before it and will be here after.
Storm Damage Roofing Across Lee, Collier and the Gulf Coast
We inspect and repair storm-damaged roofs throughout Lee County and Collier County, including Naples, Marco Island, Fort Myers, Cape Coral, Estero and Bonita Springs, and farther up the coast in Port Charlotte, Venice and Sarasota.
Answers to Common Roof Insurance Claim Questions in Florida
Can a roofer help with an insurance claim in Florida?
Yes, within limits set by Florida law. A roofer can inspect your roof, document visible damage, provide an itemized repair estimate and complete the approved work. A roofer can't interpret your policy, advise on coverage or adjust your claim unless licensed as a public adjuster.
Should a roofer be there when the adjuster inspects my roof?
Many homeowners find it helpful, because the roofer can point out the damage they documented. It's your choice, and it doesn't change who makes decisions about your claim. Let us know if you'd like us there.
Will my homeowners insurance cover my roof damage?
Only your insurance company can determine what your policy covers. Your agent or insurer is the right source for coverage questions. What we can do is document the condition of your roof and estimate the cost of repair.
Can a roofer pay or waive my insurance deductible?
No. In Florida, a contractor who knowingly pays, waives or rebates any part of an insurance deductible commits insurance fraud, a third-degree felony. You're responsible for your deductible, and any roofer who offers to cover it is a red flag.
What's the difference between a roofer and a public adjuster?
A licensed public adjuster represents you in adjusting and negotiating your insurance claim. A roofing contractor inspects, documents and repairs the roof. We're roofers, and we'll recommend you speak with a licensed professional if you need help with the claim itself.
How do I choose a roofer after storm damage?
Verify the roofer's Florida license, ask for an itemized written estimate, check reviews, and walk away from anyone offering to waive your deductible. Our guide to choosing a Florida roofer walks through each step.
Start With an Inspection and Clear Documentation
Storm damage is stressful enough without guessing at what's wrong with your roof. Call us to schedule an inspection, and we'll show you what we find and what the repair involves.